For physicians relocating to Omaha
You find out in March. You live here by July.
Match Day is March 19, 2027. Residency begins July 1, 2027. That is 15 weeks to finish medical school, sit for boards, credential, move across the country and find somewhere to live in a city most people have never driven through.
Bill has walked physicians and corporate recruits through Omaha for four decades — often before they have accepted the job — and holds the Certified Relocation Professional designation among eleven others. Not a relocation packet. Him, in the car, showing you the city.
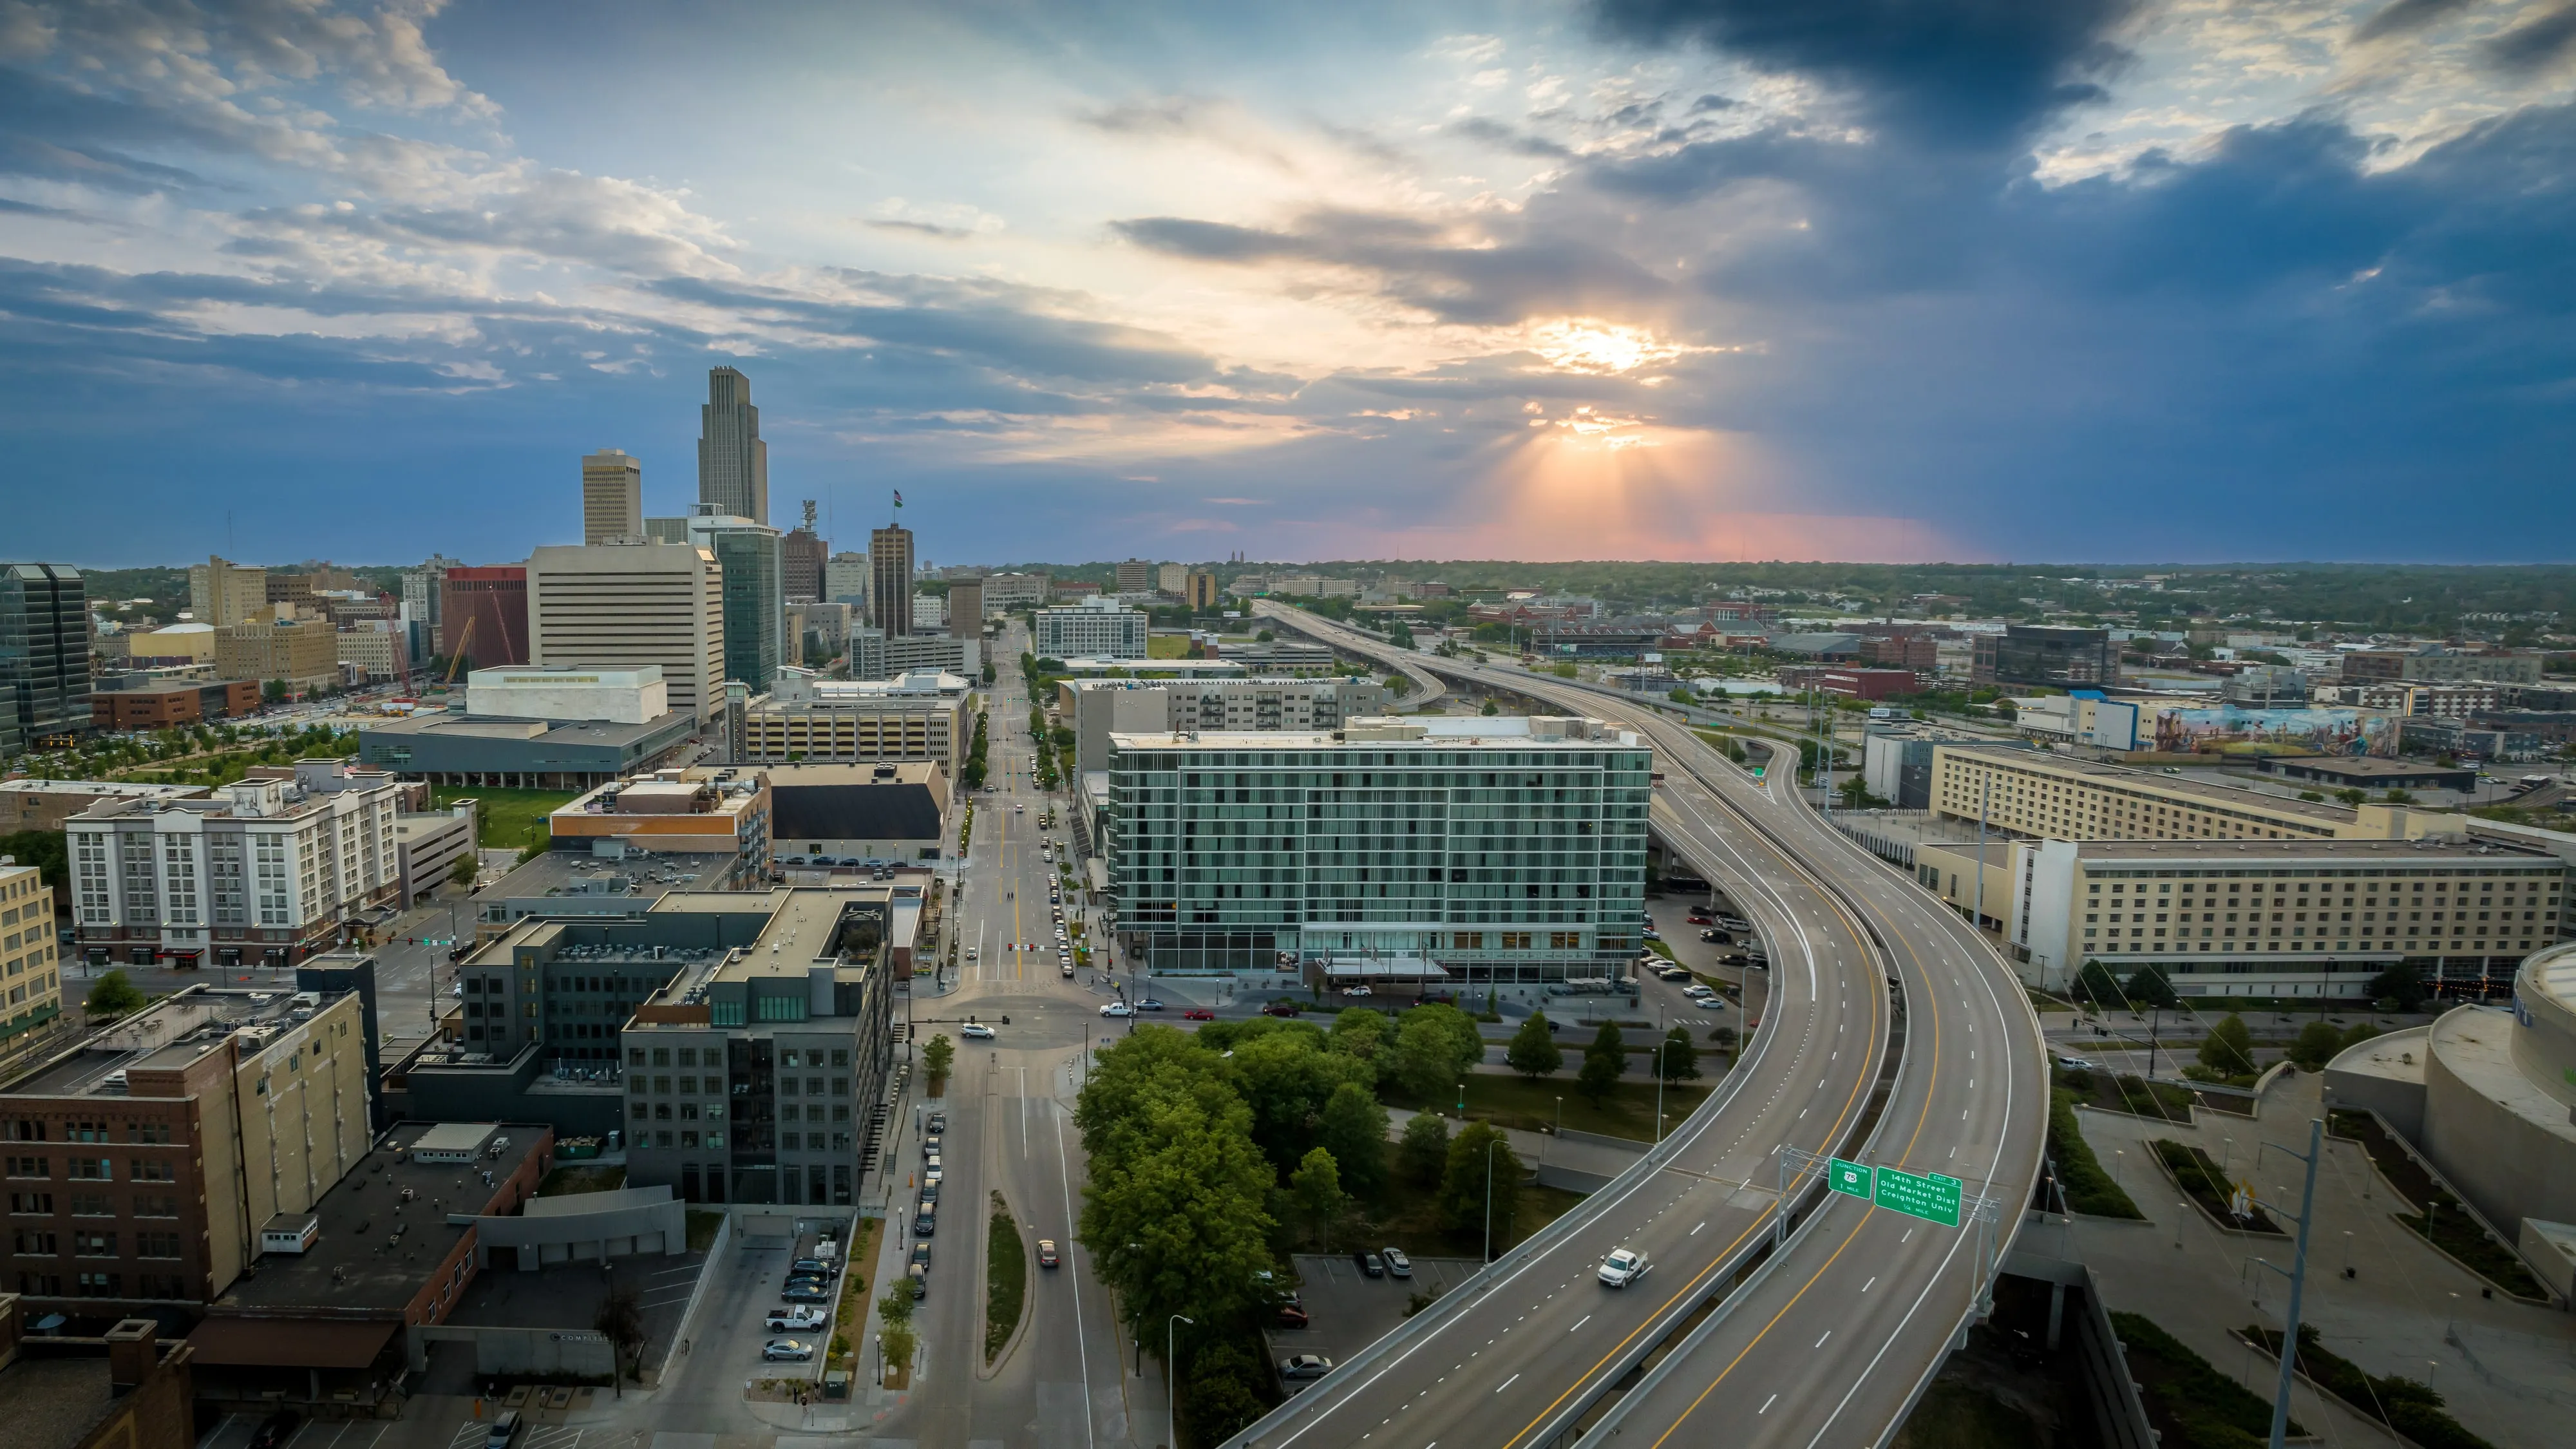
Every neighbourhood, timed to your campus
This is the question that decides where you live, and the one no national site can answer. Pick where you are going to be at six in the morning and the neighbourhoods sort themselves by how far you are from it.
The VA Medical Center on Woolworth is a few blocks away, so these times cover both.
- Field Club 5–9 min
Closest thing to walking distance from UNMC. Pre-war housing, small lots, and a short drive at any hour.
- Dundee 8–12 min
The neighbourhood most residents ask about by name. Tree canopy, a walkable few blocks, and 1920s houses.
- Aksarben & Elmwood Park 8–12 min
Newer build near the golf course and the Aksarben Village district, with the shortest run to Bergan Mercy.
- Memorial Park & Fairacres 10–14 min
The established money. Larger lots, mature trees, and a drive that works for every campus on this list.
- Old Market & downtown 10–15 min
The only part of the metro where the car is optional. Lofts and condos rather than houses.
- Rockbrook & Loveland 15–20 min
Mid-century ranches and split levels, strong elementary schools, minutes from the Dodge Street campuses.
- Westside & District 66 15–20 min
Bought for the school district as much as the house. Central to almost everything.
- Regency 16–22 min
Wooded, quiet and oddly hidden for how central it is.
- West Omaha, 132nd to 144th 20–26 min
More house per dollar, newer mechanicals, and a real drive to midtown.
- Papillion 20–27 min
Sarpy County schools and newer stock, with a reasonable run to Bergan Mercy.
- Elkhorn 27–35 min
New construction and the strongest west-side schools, at the cost of the longest commute here.
- Rockbrook & Loveland 6–10 min
Mid-century ranches and split levels, strong elementary schools, minutes from the Dodge Street campuses.
- Westside & District 66 6–10 min
Bought for the school district as much as the house. Central to almost everything.
- Memorial Park & Fairacres 8–12 min
The established money. Larger lots, mature trees, and a drive that works for every campus on this list.
- Regency 8–12 min
Wooded, quiet and oddly hidden for how central it is.
- Dundee 10–14 min
The neighbourhood most residents ask about by name. Tree canopy, a walkable few blocks, and 1920s houses.
- West Omaha, 132nd to 144th 10–16 min
More house per dollar, newer mechanicals, and a real drive to midtown.
- Aksarben & Elmwood Park 12–16 min
Newer build near the golf course and the Aksarben Village district, with the shortest run to Bergan Mercy.
- Field Club 14–18 min
Closest thing to walking distance from UNMC. Pre-war housing, small lots, and a short drive at any hour.
- Old Market & downtown 16–22 min
The only part of the metro where the car is optional. Lofts and condos rather than houses.
- Papillion 18–25 min
Sarpy County schools and newer stock, with a reasonable run to Bergan Mercy.
- Elkhorn 20–28 min
New construction and the strongest west-side schools, at the cost of the longest commute here.
- Aksarben & Elmwood Park 5–9 min
Newer build near the golf course and the Aksarben Village district, with the shortest run to Bergan Mercy.
- Field Club 8–12 min
Closest thing to walking distance from UNMC. Pre-war housing, small lots, and a short drive at any hour.
- Dundee 10–14 min
The neighbourhood most residents ask about by name. Tree canopy, a walkable few blocks, and 1920s houses.
- Memorial Park & Fairacres 10–14 min
The established money. Larger lots, mature trees, and a drive that works for every campus on this list.
- Rockbrook & Loveland 10–14 min
Mid-century ranches and split levels, strong elementary schools, minutes from the Dodge Street campuses.
- Westside & District 66 10–14 min
Bought for the school district as much as the house. Central to almost everything.
- Regency 12–16 min
Wooded, quiet and oddly hidden for how central it is.
- Old Market & downtown 12–17 min
The only part of the metro where the car is optional. Lofts and condos rather than houses.
- West Omaha, 132nd to 144th 15–20 min
More house per dollar, newer mechanicals, and a real drive to midtown.
- Papillion 15–22 min
Sarpy County schools and newer stock, with a reasonable run to Bergan Mercy.
- Elkhorn 24–32 min
New construction and the strongest west-side schools, at the cost of the longest commute here.
- West Omaha, 132nd to 144th 5–9 min
More house per dollar, newer mechanicals, and a real drive to midtown.
- Regency 7–11 min
Wooded, quiet and oddly hidden for how central it is.
- Rockbrook & Loveland 10–15 min
Mid-century ranches and split levels, strong elementary schools, minutes from the Dodge Street campuses.
- Westside & District 66 10–15 min
Bought for the school district as much as the house. Central to almost everything.
- Elkhorn 12–18 min
New construction and the strongest west-side schools, at the cost of the longest commute here.
- Memorial Park & Fairacres 14–20 min
The established money. Larger lots, mature trees, and a drive that works for every campus on this list.
- Dundee 16–22 min
The neighbourhood most residents ask about by name. Tree canopy, a walkable few blocks, and 1920s houses.
- Aksarben & Elmwood Park 18–24 min
Newer build near the golf course and the Aksarben Village district, with the shortest run to Bergan Mercy.
- Field Club 20–26 min
Closest thing to walking distance from UNMC. Pre-war housing, small lots, and a short drive at any hour.
- Old Market & downtown 22–28 min
The only part of the metro where the car is optional. Lofts and condos rather than houses.
- Papillion 22–30 min
Sarpy County schools and newer stock, with a reasonable run to Bergan Mercy.
Typical off-peak driving times, approximate and offered for comparison rather than as a promise. A 2am call and a 7:40am school run are different roads. Before you write an offer, drive it at the hour you will actually be driving it — we will tell you where to start from.
Should you buy at all?
Most agents will not ask you this, because the answer is sometimes no. It turns almost entirely on how long you will be here — so start there rather than with a house.
The number nobody tells residents: buying and then selling costs roughly eight to ten percent of the value of the house across the two transactions once commission, title, closing costs and the things a buyer asks for are counted. That is the hurdle any short hold has to clear. This is a rule of thumb and a starting point for a conversation with your own accountant, not tax or investment advice — we are neither.
The 15 weeks, laid out
Built around a July 1 start. If you are an attending starting on another date, put yours in and it recalculates — the shape does not change, only the dates.
-
Before you even know where you matched
Talk to a lender about a physician mortgage. Not to borrow — to find out what you qualify for with $250,000 of student debt, because the answer determines whether this is a conversation about buying at all.
-
Match Day
You find out on a Friday, with everyone watching. The weekend is for celebrating. Monday is for the lender.
-
See the city, in a car, with someone who knows it
A day. It is the single highest-leverage thing you can do, and almost nobody does it because it feels premature. It is not — it prevents the expensive mistake of choosing a neighbourhood from a map.
-
Narrow to two neighbourhoods and set the number
Pre-approval in hand. Everything after this is inventory rather than decisions.
-
Offer accepted
Eight weeks out gives room for an appraisal to come in low, an inspection to find something, or a seller to move slowly — any of which is survivable with time and none of which is with four weeks.
-
Inspection done and responded to
Where transactions are actually won or lost. Appraisal runs in parallel.
-
Clear to close, and book the movers
Not before. A truck scheduled against a date that has not cleared underwriting is how people end up in a hotel with their furniture in Kansas.
-
Close, and have ten days that are not about a house
Orientation and credentialing will take everything you have. Deliberately leaving slack here is the difference between arriving rested and arriving already behind.
-
Day one
You know the drive because you have already done it.
Physician mortgages
Six questions that decide whether it is a good deal
A physician mortgage typically means a low or zero down payment, no mortgage insurance, and underwriting that treats student debt and a signed contract differently from a conventional loan. Typically. The terms vary a great deal between lenders, and the variation is where the money is. We are not a lender, we take no part in your financing and we are paid nothing for pointing you at one — but we can tell you what to ask.
- Student debt
- Does the program exclude student loan debt from debt-to-income entirely, or only debt that is deferred or on an income-driven plan? The difference is enormous at $250,000 of it and the answer varies by lender.
- Contract as income
- Will you underwrite on a signed employment contract before I have a first pay stub, and how many days before the start date will you close?
- Down payment and PMI
- What down payment is required at my price point, and at what point does mortgage insurance reappear?
- The long view
- How does this rate compare with a conventional loan once I have twenty percent equity, and what does refinancing out of it cost?
- Who qualifies
- Are residents, fellows and attendings on different terms, and does my degree qualify — programs differ on DO, DDS, DVM and PharmD.
- Moving again
- If I match into a fellowship elsewhere in three years, what does selling early look like on this product?
If you cannot get here before you buy
Plenty of matched residents never see the house in person. It works, provided the person standing in it is genuinely looking on your behalf rather than selling you something.
- A live walkthrough, not a tour
- A video call where you say “go back to that ceiling” and someone does — opens the panel box, runs the taps, goes outside to look at where the water leaves the gutters.
- The street at the hour you will live on it
- A weekday evening, not a Sunday morning. Traffic, parking, noise, how dark it gets.
- Somebody willing to say no
- The hardest part and the whole point. You will be exhausted, three states away and under time pressure, and it is very easy to talk yourself into a house. If it is wrong we will tell you, including when telling you costs us the sale.
No obligation, no drip campaign
Tell us where you matched and we will work backwards from July 1.
Enough that the first call is useful rather than spent gathering facts. Everything past your name and email is optional.
Sent.
It is with Bill Black now. If you need an answer sooner than an email, call 402.681.1576 — that is his own line.
Also worth a look: the neighbourhood guides, employer relocation guides if a partner is job-hunting, and how buying here actually goes.